By David Parks · eXp Realty · The Apollo Group · 2 min read
Lenders look at your income, debts, credit, and down payment to set a maximum. A better question is what monthly payment feels comfortable once taxes, insurance, and maintenance are included.

Lenders consider your debt-to-income ratio, which compares monthly debts to gross monthly income. A common upper limit for conventional loans is in the mid-40 percent range, though it varies by loan type and lender.
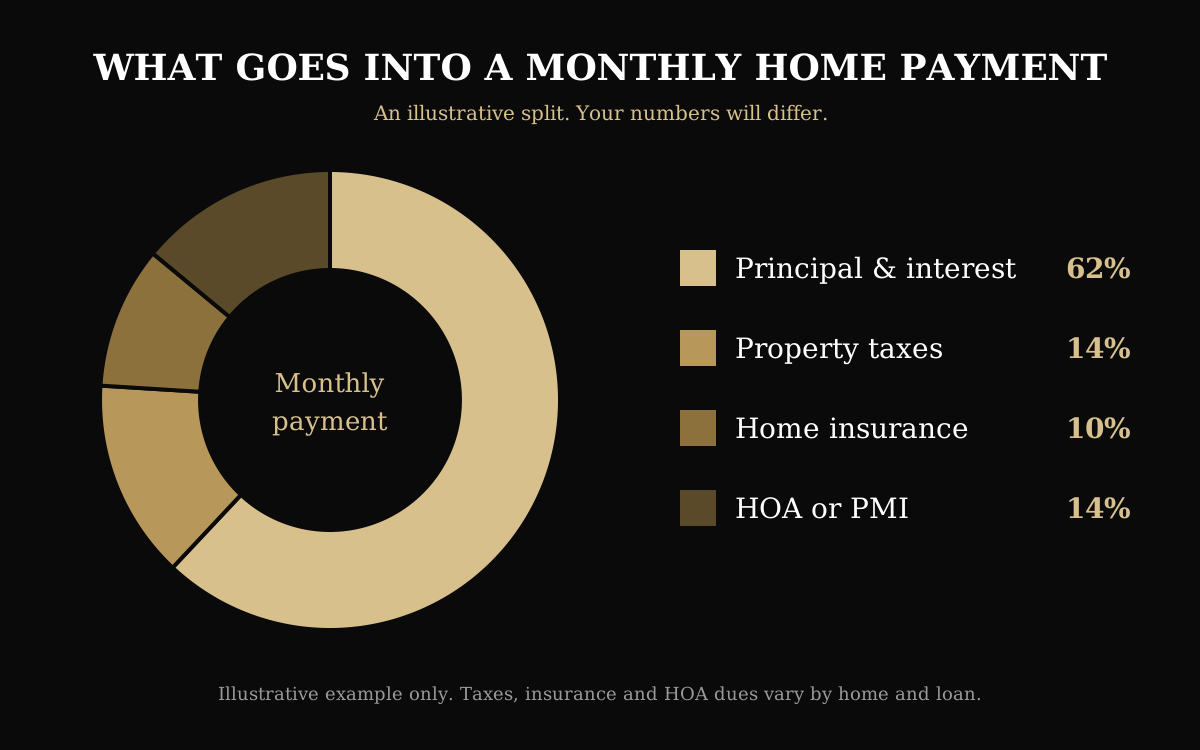
Utilities, maintenance, commuting, childcare, and savings goals all affect what fits. A planning guide is to budget about one percent of the home’s value each year for repairs.
Use the mortgage calculator to test different prices and down payments. Then talk with a lender about pre-approval so you have exact numbers.
Being pre-approved for more than you want to spend is fine. Choose a payment you can sustain through life’s changes.
This article is general information, not legal, tax, financial or inspection advice. Every home and situation is different, so confirm details with a licensed inspector, lender, attorney or tax professional.
David is a Greater Denver real estate advisor with eXp Realty and The Apollo Group (Colorado broker license FA100103211). He has closed more than $55 million in volume, earned eXp Icon status in 2025, and holds a 5.0 rating on Zillow from 27 verified reviews.
Denver market updates, new listings, and local tips — no spam, unsubscribe anytime.