By David Parks · eXp Realty · The Apollo Group · 2 min read
A housing bubble happens when prices rise far beyond what fundamentals support, often fueled by risky lending. Today’s market differs from the mid-2000s in lending standards and homeowner equity, though local conditions still vary.
In the lead-up to 2008, many loans were made with little documentation and teaser rates, and many homeowners had little equity. When payments reset or prices fell, many were unable to refinance or sell.
Lending standards are generally stricter, most borrowers have fixed-rate loans, and many homeowners have substantial equity. Limited supply of homes has also played a role in price levels.
Make sure the purchase fits your budget and timeline, not just the headlines. A home is best seen as a long-term decision. Local markets can soften or cool even without a crash, so talk with an agent about conditions in your neighborhood.
This article is general information, not legal, tax, financial or inspection advice. Every home and situation is different, so confirm details with a licensed inspector, lender, attorney or tax professional.
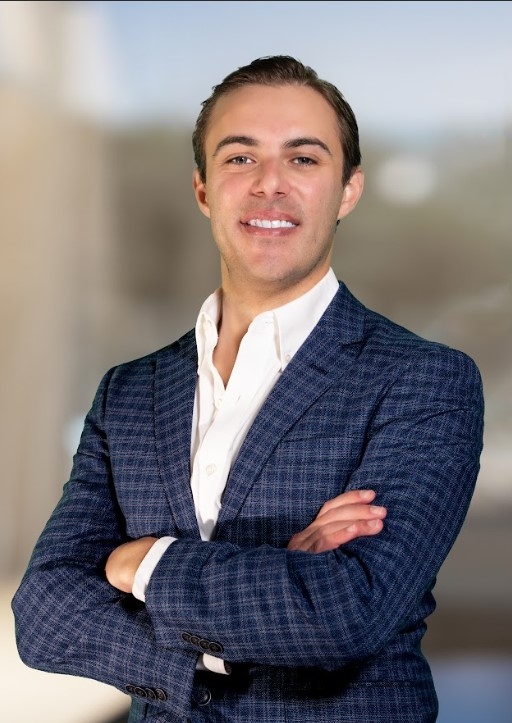
David is a Greater Denver real estate advisor with eXp Realty and The Apollo Group (Colorado broker license FA100103211). He has closed more than $55 million in volume, earned eXp Icon status in 2025, and holds a 5.0 rating on Zillow from 27 verified reviews.
Denver market updates, new listings, and local tips — no spam, unsubscribe anytime.